What Is Law Firm Accounting?
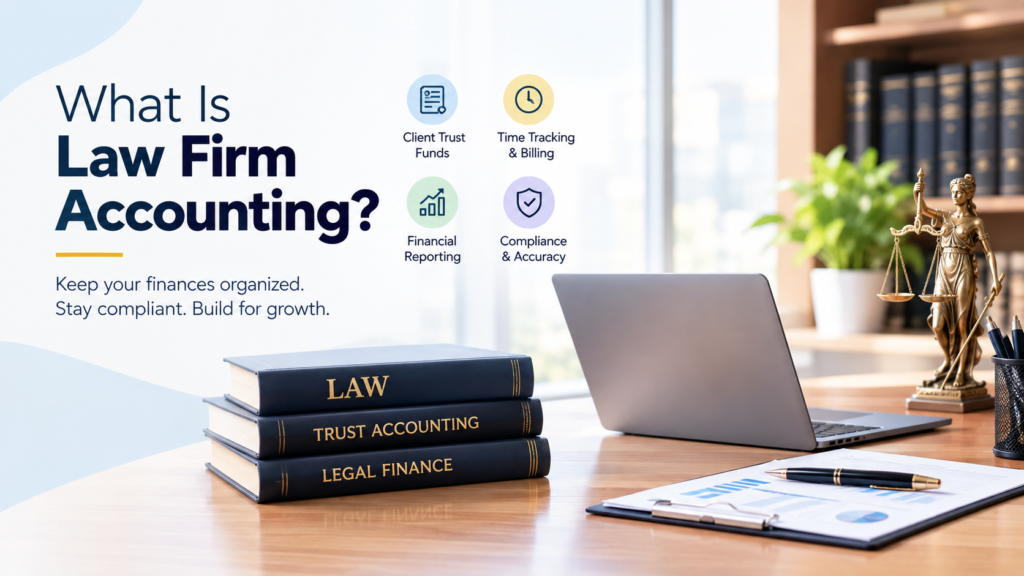
Law firm accounting is the process of recording, organizing, monitoring, and reporting all financial activities within a legal practice. While every business relies on accounting, legal firms operate under additional ethical and regulatory responsibilities that make their accounting requirements far more complex.
A law firm’s accounting system doesn’t just track income and expenses. It also manages client trust funds, records billable hours, processes legal billing, prepares financial reports, handles payroll, and ensures compliance with legal and accounting standards.
Law firms cannot mix client funds with operating funds. Client retainers and settlement amounts must remain in separate trust accounts until they are earned or disbursed according to legal guidelines. Even a minor accounting mistake can create compliance issues, damage client trust, or expose the firm to disciplinary action.
For this reason, many growing practices transition toward managed bookkeeping services to maintain dedicated legal accounting systems that seamlessly align financial records with legal practice workflows.
What Is Law Firm Finance?
While accounting focuses on recording financial information, law firm finance is about using that information to make strategic business decisions. Think of accounting as documenting what has already happened, while finance helps determine what should happen next.
Law firm finance includes:
- Budget planning
- Cash flow forecasting
- Profitability analysis
- Revenue planning
- Investment decisions
- Risk management
- Business expansion planning
Strong law firm financial management enables partners to understand:
- Which practice areas generate the highest profits
- Which attorneys contribute the most revenue
- Whether hiring additional staff is financially viable
- How much working capital the firm should maintain
- When technology investments are financially justified
Instead of making decisions based on assumptions, firms can rely on accurate financial data to support sustainable growth.
When accounting and finance work together, they create a complete financial management system that improves efficiency, profitability, and long-term stability.
Why Effective Accounting Is Essential for Law Firms?
Effective accounting helps law firms stay financially organized, meet regulatory requirements, and make informed business decisions with confidence.
Here are the key reasons why effective accounting is essential for law firms.
1. Ensures Compliance with Legal and Ethical Standards
Law firms have a legal obligation to manage client funds responsibly. Proper trust accounting ensures retainers, settlements, and other client funds remain separate from business operating accounts.
Maintaining accurate records also prepares firms for audits and helps them comply with state bar regulations, tax requirements, and professional accounting standards.
2. Improves Cash Flow Management
Many law firms struggle with delayed payments, outstanding invoices, and inconsistent cash flow. A structured law firm cash flow management process helps firms:
- Send invoices on time.
- Track outstanding payments.
- Follow up with clients consistently.
- Forecast future cash requirements.
- Avoid unnecessary financial pressure.
3. Supports Better Business Decisions
Reliable financial reports provide valuable insights into business performance. Firm owners can identify:
- Profitable practice areas
- High operating costs
- Revenue trends
- Client payment behavior
- Budget performance
These insights help leaders make confident decisions about hiring, expansion, pricing, and investments.
4. Strengthens Client Trust
Clients expect complete transparency when their money is involved. Accurate financial records, clear invoices, and properly managed trust accounts demonstrate professionalism and reinforce client confidence in the firm’s operations.
5. Increases Profitability
Strong accounting systems help firms identify unnecessary expenses, recover missed billable hours, improve collections, and monitor profitability more effectively. Over time, these improvements contribute to stronger financial performance and sustainable business growth.
Core Components of Law Firm Accounting
An efficient accounting system is built on several interconnected processes that work together to support daily financial operations.
1. Bookkeeping
Law firm bookkeeping forms the foundation of every accounting system. It involves recording daily financial transactions such as:
- Client payments
- Vendor invoices
- Office expenses
- Payroll
- Bank deposits
- Operating costs
2. Trust Accounting
Trust accounts, often referred to as IOLTA accounts, hold client money separately until those funds are earned or legally disbursed.
Proper trust accounting for attorneys includes:
- Recording every deposit and withdrawal.
- Maintaining separate client ledgers.
- Performing regular reconciliations.
- Preventing commingling of funds.
- Maintaining complete audit trails.
3. Legal Billing and Time Tracking
Most firms generate revenue through billable hours. Accurate legal billing depends on recording time promptly, assigning work to the correct matter, and applying the appropriate billing rates.
Modern billing systems also support flat-fee arrangements, retainers, contingency fees, and subscription-based legal services.
4. Accounts Receivable and Payable
Accounts receivable tracks outstanding client invoices, while accounts payable manages payments owed to vendors and service providers. Monitoring both helps firms improve collections, control expenses, and maintain healthy cash flow.
5. Payroll Management
Law firm payroll involves much more than paying employee salaries. It includes:
- Attorney compensation
- Employee benefits
- Payroll taxes
- Partner distributions
- Bonus calculations
6. Expense Tracking
Every legal practice incurs operating costs that directly impact profitability. Common expenses include:
- Office rent
- Legal research subscriptions
- Court filing fees
- Marketing expenses
- Software subscriptions
- Professional insurance
- Business travel
Tracking these costs helps firms control spending, improve budgeting, and identify opportunities to reduce unnecessary expenses.
For many expanding law practices, handling complex partner compensation, bonus structures, and employee tax withholdings internally can become overwhelming. Implementing specialized payroll processing & outsourcing ensures timely compensation while keeping the firm fully compliant with tax regulations.
How Law Firm Accounting Works: Step-by-Step Process?
An efficient accounting system follows a structured workflow that keeps financial records accurate, ensures compliance, and supports better decision-making. While the exact process may vary depending on the firm’s size and practice areas, the following steps form the foundation of effective law firm accounting.
1. Record Financial Transactions
This includes client payments, retainers, invoices, payroll, office expenses, court filing fees, vendor payments, and tax obligations. Accurate transaction recording prevents reporting errors and provides a reliable financial history for the firm.
2. Manage Client Trust Accounts
Money received as retainers or settlements must be deposited into separate trust accounts until it is earned or distributed. Each client should have an individual ledger that clearly records deposits, withdrawals, and the remaining balance.
Regular reconciliation ensures that trust account balances always match client records and bank statements.
3. Track Billable Hours
Attorneys should record time as work is completed rather than relying on memory at the end of the day. Accurate time tracking reduces revenue leakage and ensures clients receive transparent invoices.
Many firms integrate time tracking directly with their law firm accounting software, making the billing process faster and more accurate.
4. Generate Invoices and Collect Payments
Once legal work is completed, invoices should be generated promptly.
A clear invoice should include:
- Services provided
- Billable hours
- Applicable rates
- Expenses incurred
- Taxes, where applicable
- Payment terms
5. Reconcile Accounts Regularly
Bank accounts, trust accounts, and accounting records should be reconciled every month. Regular reconciliation helps identify duplicate entries, missing transactions, banking errors, or unauthorized activity before they become serious issues.
6. Prepare Financial Reports
At the end of each reporting period, accounting data is converted into meaningful financial reports. These reports help partners understand profitability, monitor expenses, review cash flow, and evaluate overall business performance.
7. Review and Plan Ahead
Financial reports should be reviewed regularly to identify trends, control costs, set budgets, and plan future investments. This is where accounting supports smarter law firm financial management and long-term business growth.
Key Financial Metrics Every Law Firm Should Track
Below are the key metrics that help partners evaluate profitability, operational efficiency, and financial stability.
-
Revenue Growth
Revenue growth measures whether the firm’s income is increasing over time. Consistent growth usually indicates strong client demand, effective pricing strategies, and healthy business development.
-
Net Profit Margin
Profit margin shows how much profit remains after covering all operating expenses. A healthy margin indicates that the firm is generating sufficient income while managing costs effectively.
-
Collection Rate
The collection rate measures how much of the billed amount is actually collected from clients. Low collection rates often point to weak billing practices, delayed follow-ups, or client payment issues.
-
Realization Rate
The realization rate compares billable work with the amount ultimately billed and collected. A declining realization rate may indicate excessive write-offs, discounted fees, or inefficient time tracking.
-
Billable Hours Utilization
This metric measures how much of an attorney’s working time is spent on revenue-generating legal work. Higher utilization generally improves profitability, provided workloads remain sustainable.
-
Accounts Receivable Days
This KPI shows how long clients take to pay outstanding invoices. The lower the number, the healthier the firm’s cash flow.
-
Average Revenue Per Lawyer
Calculating revenue generated per attorney helps firms evaluate productivity across practice areas and identify opportunities for improvement.
Essential Financial Statements for Law Firms
Every law firm should prepare regular financial statements to understand its financial position and support strategic planning.
1. Balance Sheet
The balance sheet provides a snapshot of the firm’s financial position at a specific point in time.
It includes:
- Assets such as cash, equipment, and accounts receivable
- Liabilities such as loans and unpaid expenses
- Owners’ equity or retained earnings
2. Income Statement (Profit and Loss Statement)
The income statement summarizes the firm’s revenue, expenses, and net profit over a reporting period. By reviewing this report regularly, firms can identify profitable practice areas, monitor expenses, and improve overall financial performance.
3. Cash Flow Statement
A profitable firm can still experience financial difficulties if cash isn’t available when needed.
The cash flow statement tracks how money moves into and out of the business through:
- Operating activities
- Investing activities
- Financing activities
4. Statement of Owner’s Equity
For partnerships and privately owned law firms, this report tracks changes in owners’ capital, retained earnings, and partner distributions over time.
Best Practices for Effective Law Firm Accounting
The following practices help reduce errors, improve efficiency, and maintain compliance.
- Keep Client Funds Separate: Client money should never be mixed with the firm’s operating funds. Maintaining separate trust accounts is one of the most important legal and ethical responsibilities for every law firm.
- Maintain Accurate Bookkeeping: Recording transactions daily prevents missing information and simplifies month-end reporting. Accurate legal bookkeeping also makes audits, tax preparation, and financial reporting much easier.
- Automate Routine Accounting Tasks:
Modern law firm accounting software can automate repetitive work such as:
- Time tracking
- Invoice generation
- Expense categorization
- Bank reconciliation
- Financial reporting
Automation improves accuracy while allowing staff to focus on higher-value work.
- Review Financial Reports Monthly: Financial reports should not be prepared only for tax season. Monthly reviews help identify revenue trends, monitor expenses, and detect financial issues before they become larger problems.
- Monitor Budgets Regularly: Creating a realistic law firm budgeting plan allows firms to control spending while preparing for future growth. Budgets should be reviewed throughout the year and adjusted whenever business conditions change.
- Work With Legal Accounting Professionals: As firms grow, working with experienced accountants who understand the legal industry can improve compliance, strengthen reporting accuracy, and support better financial planning.
Common Accounting Challenges Faced by Law Firms
Even well-managed firms face accounting challenges that affect profitability and operational efficiency.
1. Managing Trust Account Compliance
Trust accounting remains one of the biggest compliance risks for legal practices. Small errors in recording client funds or reconciliation can result in regulatory penalties and damage client confidence.
2. Delayed Client Payments
Late payments reduce available cash and make it difficult to cover operating expenses. Clear billing policies, automated reminders, and multiple payment options can significantly improve collections.
3. Revenue Leakage
Missed billable hours, delayed invoicing, and incorrect billing rates often result in lost revenue. Accurate time tracking and integrated billing systems help prevent these issues.
4. Expense Control
Without careful monitoring, operating expenses can gradually reduce profit margins. Regular expense reviews help firms identify unnecessary costs and improve financial efficiency.
5. Tax Compliance
Managing payroll taxes, business taxes, and deductible expenses requires accurate records throughout the year. Waiting until tax season often increases the risk of errors and missed deductions.
6. Data Security
Financial records contain highly confidential information. Law firms should implement secure accounting systems, role-based access controls, encrypted backups, and regular software updates to protect sensitive client and financial data.
How to Choose the Right Accounting Solution for Your Law Firm?
Every law firm has different financial needs, so selecting the right accounting solution requires careful evaluation. Whether you’re searching for software or considering outsourced accounting services, focus on long-term value rather than just upfront cost.
When evaluating an accounting solution, consider the following:
-
Compliance Support
Choose software that supports legal industry requirements, including trust accounting and detailed financial reporting.
-
Ease of Use
Your accounting system should simplify daily work rather than create additional administrative tasks. Look for an intuitive interface that attorneys and finance staff can learn quickly.
-
Integration Capabilities
The software should integrate with your existing:
- Practice management system
- Time tracking tools
- Payroll software
- Payment gateways
- Document management platform
Integrated systems reduce duplicate data entry and improve overall efficiency.
-
Scalability
As your firm grows, your accounting system should be able to handle additional users, clients, offices, and reporting requirements without requiring a complete replacement.
-
Security
Financial records contain highly sensitive client information. Choose solutions that provide encrypted data storage, automatic backups, user permissions, and multi-factor authentication.
For many small and mid-sized firms, combining specialised software with professional accounting support provides the best balance between efficiency and compliance.
Final Thoughts
Strong financial management is the backbone of every successful legal practice. By implementing effective law firm accounting & finance processes, firms can maintain compliance, protect client trust funds, improve cash flow, and make better business decisions. From accurate bookkeeping and legal billing to financial reporting and budgeting, every aspect of accounting contributes to long-term stability and profitability.
Investing in the right law firm accounting software and following proven best practices can reduce administrative burdens while increasing efficiency. As your firm grows, a well-managed accounting system will help you stay compliant, strengthen financial performance, and build a solid foundation for sustainable success.
Frequently Asked Questions
What are the most important financial metrics for law firms?
Key metrics include revenue growth, net profit margin, collection rate, realisation rate, billable hours utilisation, accounts receivable days, and average revenue per lawyer.
How often should a law firm review its financial reports?
Monthly financial reviews are recommended to monitor profitability, control expenses, improve collections, and support informed business decisions.
Can small law firms outsource accounting?
Yes. Many small firms outsource bookkeeping, payroll, tax preparation, and financial reporting to experienced accounting professionals to reduce costs and improve compliance.
What are the best practices for law firm accounting?
The most effective practices include maintaining separate trust accounts, keeping accurate bookkeeping records, automating billing, reconciling accounts monthly, monitoring financial KPIs, and using specialised legal accounting software.
What financial statements should every law firm prepare?
Every law firm should regularly prepare a balance sheet, income statement (profit and loss statement), cash flow statement, and, where applicable, a statement of owner’s equity.